
Executive Summary
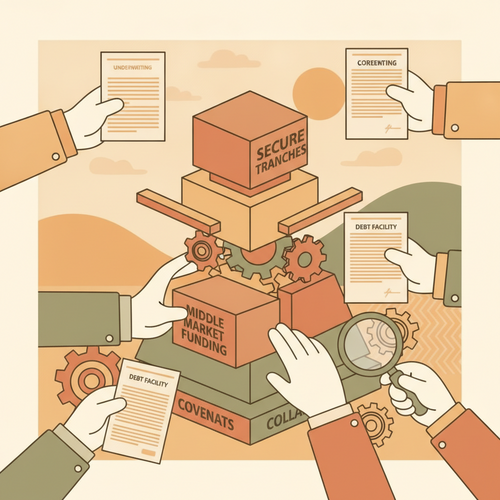
- Private debt underwriting demands rigorous analysis of deal sponsors, operational metrics, and robust covenant packages.
- Structuring first-lien senior secured tranches mitigates lender risk through strong collateral positions and priority claims.
- Middle market dynamics necessitate deep expertise in bespoke credit solutions and meticulous legal documentation.
Navigating Private Debt: First-Lien Senior Secured Foundations
Private debt has emerged as a critical capital source for middle market enterprises. It provides tailored financing beyond traditional bank lending. Understanding its core components is paramount for investors. This segment often involves direct lending by non-bank institutions.
First-lien senior secured debt holds the highest claim on a borrower’s assets. This priority applies in the event of default or bankruptcy. Such positioning significantly reduces lender risk exposure. It contrasts sharply with subordinated or mezzanine debt.
Middle market firms typically require flexible, relationship-driven capital. Private debt funds fill this void effectively. They offer speed, certainty, and customized terms. This specialized approach differentiates them from syndicated loan markets. Their underwriting processes are distinct.
Underwriting Due Diligence: Beyond Financial Statements
Comprehensive due diligence forms the bedrock of sound private debt underwriting. It extends beyond mere historical financial analysis. Lenders scrutinize a company’s operational viability and management capabilities. Evaluating the leadership team is a crucial qualitative factor.
Strategic market positioning and competitive advantages are also assessed. Underwriters analyze industry trends and customer concentration. They validate revenue streams and expenditure forecasts rigorously. Sensitivity analyses and stress testing are standard procedures.
Understanding a borrower’s underlying business model is critical. This includes assessing its competitive landscape and long-term sustainability. Cash flow predictability under various economic scenarios informs credit decisions. Robust financial modeling supports these complex evaluations.
Expert Insight: “Effective private debt underwriting demands a proprietary lens. We assess management depth and market defensibility as heavily as historical EBITDA.”
Covenant Structures and Financial Maintenance Metrics
Covenants are indispensable tools for lender protection in private debt. They establish specific financial and operational parameters. Breaching these triggers typically constitutes a default event. This allows lenders to intervene or accelerate repayment.
Key financial maintenance covenants often include leverage ratios. These limit the borrower’s total debt relative to its EBITDA. Another common metric is the fixed charge coverage ratio (FCCR). It ensures sufficient cash flow to cover debt service and capital expenditures.
Negative covenants restrict actions detrimental to lenders. These might prohibit excessive dividends or asset sales. Positive covenants compel specific actions, like providing timely financial reports. First-lien structures often feature tighter covenant packages. These provide enhanced control and early warning signals.
In middle markets, traditional covenants remain prevalent. “Covenant-lite” structures, common in large-cap markets, are less frequent. This provides greater protection for direct lenders. Covenants are carefully negotiated to balance borrower flexibility and lender security.
Collateral Analysis and Valuation Methodologies
Collateral underpins the “secured” aspect of first-lien debt. Lenders identify and value specific assets securing the loan. This often includes accounts receivable, inventory, and intellectual property. Real estate and fixed assets also serve as crucial security.
Robust collateral coverage directly mitigates credit risk. Valuation methodologies vary by asset class. For current assets, an asset-based lending (ABL) approach is common. This involves frequent appraisals and borrowing base certificates.
For enterprise value-driven loans, the entire business serves as collateral. Lenders assess its going-concern value. This typically involves discounted cash flow (DCF) or comparable company analysis. Due diligence extends to perfecting security interests legally.
Market Warning: Over-reliance on distressed asset valuations can lead to recovery shortfalls. Conservative collateral assessments are always prudent.
Intercreditor Agreements and Tranche Specificity
Multi-tranche debt structures necessitate formal intercreditor agreements. These legal documents define the rights and priorities of different lenders. They are critical when senior and junior debt exist simultaneously. Clear delineation prevents disputes during distress.
In first-lien/second-lien structures, the intercreditor agreement dictates payment waterfalls. It outlines enforcement rights and foreclosure procedures. Junior lenders agree to subordinate their claims. This includes both payment and remedies.
Unitranche facilities blend senior and junior debt into a single instrument. While simplified for the borrower, the lender typically maintains an internal intercreditor. This internal agreement still specifies the allocation of risk and return among participating lenders. Senior debt always retains its priority status within these arrangements.
Pricing Dynamics and Yield Enhancement Strategies
Private debt pricing reflects a complex interplay of risk and market demand. Key components include a floating base rate, like SOFR, plus a credit spread. Upfront fees and original issue discounts (OID) enhance overall lender yield significantly.
Credit spreads compensate for specific borrower risk profiles. Industry cyclicality, financial performance, and management strength influence these spreads. Longer maturities or bespoke structures often command higher pricing. Demand for the specific credit profile also plays a role.
Yield enhancement strategies involve negotiating call protection and prepayment penalties. These compensate lenders for foregone interest income. SOFR floors protect against declining base rates. This ensures a minimum yield even in low-interest-rate environments.
Legal Documentation and Closing Mechanics
Robust legal documentation is non-negotiable in private debt. The term sheet serves as the initial framework. It outlines principal terms, conditions, and covenants. This preliminary agreement guides the more extensive legal drafting process.
The definitive loan agreement details all contractual obligations. It covers representations, warranties, and events of default. Security agreements perfect the lender’s interest in collateral. Guarantees from sponsors or affiliates provide additional credit support.
Closing mechanics involve satisfying all conditions precedent. These often include legal opinions, insurance certificates, and corporate authorizations. A meticulous closing checklist is essential. It ensures all requirements are met before funding the facility.
Market Trends and Portfolio Management in Private Debt
The private debt market continually evolves. Recent trends show increased dry powder and sustained demand from borrowers. Sponsor-backed deals remain a significant driver of origination volume. Lenders must adapt to changing market dynamics and competition.
Effective portfolio management is crucial post-closing. Lenders continuously monitor borrower performance against covenants. Early warning indicators, such as declining margins or liquidity issues, trigger proactive engagement. This mitigates potential losses.
Regular reviews of financial statements and operational updates are standard. Lenders may engage in portfolio diversification strategies. This spreads risk across various industries and geographies. Proactive credit management is vital for sustained portfolio health.
Conclusion
Structuring first-lien senior secured tranches in middle markets demands specialized expertise. A deep understanding of underwriting dynamics is paramount. It involves rigorous due diligence, robust covenant implementation, and meticulous collateral analysis. These elements ensure lender protection and sustainable returns.
Effective intercreditor arrangements are vital in multi-tranche scenarios. Strategic pricing and comprehensive legal documentation solidify deal integrity. Continuous portfolio management and adaptation to market trends are essential for success. How will your firm enhance its private debt underwriting capabilities to capture market opportunities?