
Executive Summary
- Collateralized Loan Obligation Tranching reallocates credit default risk across structured investor risk profiles.
- Cash flow priority waterfalls guarantee senior AAA debt protection before equity distributions occur.
- Yield spreads reflect credit ratings, loss absorption capacity, subordination levels, and underlying loan quality.
Understanding Collateralized Loan Obligation Tranching Mechanics
Structured credit markets rely heavily on specialized securitization vehicles. Collateralized loan obligations represent a dominant force in corporate debt financing. These vehicles pool hundreds of senior secured corporate loans. Portfolio managers actively select and manage these underlying credit assets.
Collateralized Loan Obligation Tranching creates distinct securities from one single asset pool. The issuer splits cash flows into prioritized debt and equity classes. Each class exhibits unique risk profiles, credit ratings, and coupon yields. This structural partitioning appeals to diverse institutional capital pools.
Senior debt holders receive strict payment priority over junior investors. Conversely, equity holders absorb initial default losses within the collateral pool. The securitization process converts illiquid corporate loans into rated marketable notes. Yield spreads expand progressively as debt position moves down the structure.
Financial engineering dictates the exact size and leverage of every layer. Market demand drives the liability structure during the deal execution phase. Asset managers balance funding costs against asset portfolio yields to maximize equity returns.
The Waterfall Structure: Prioritizing Cash Flow Distribution
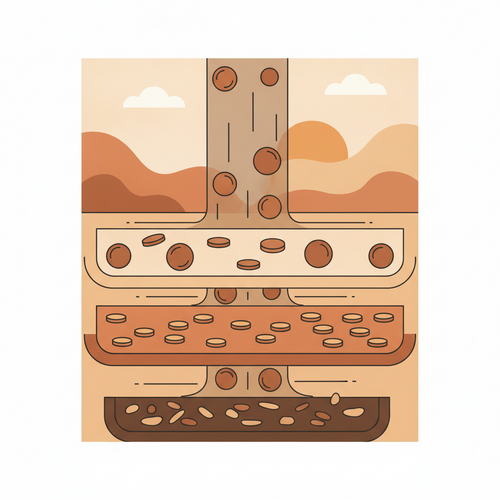
The cash flow waterfall serves as the structural foundation of CLO vehicles. Principal and interest collections follow explicit legal rules. The trustee collects coupon payments from corporate borrowers monthly or quarterly. The administrator then distributes cash strictly according to the tranche hierarchy.
Senior administrative fees take first priority in the cash distribution sequence. Senior AAA tranche noteholders receive contractual coupon payments immediately after fees. Cash flows then flow sequentially through AA, A, BBB, and BB debt classes. Equity holders receive residual cash flows only after all debt obligations are satisfied.
Coverage tests act as protective triggers within the waterfall mechanism. Overcollateralization tests measure collateral par value against outstanding debt principal. Interest coverage tests compare loan interest income against mandatory tranche interest payments. Failing a coverage test immediately halts distributions to junior tranches.
When coverage tests fail, cash flows divert to redeem senior debt principal. This automatic deleveraging restores required collateral ratios quickly. Subordinated investors lose current income until coverage ratios normalize. This structural feature safeguards senior debt ratings during market downturns.
Deconstructing Yield Spreads Across Credit Ratings
Yield spreads reflect the compensation required for taking incremental credit risk. Senior AAA notes offer the narrowest reference spreads over benchmark rates like SOFR. Investors accept lower yields in exchange for maximum credit protection. AAA tranches benefit from substantial loss-absorbing subordination underneath them.
Mezzanine debt tranches spanning AA to BBB offer intermediate yield spreads. These notes face higher credit risk during broad economic recessions. Rating agencies require lower subordination levels for mezzanine notes than senior classes. Consequently, pricing reflects modest credit downgrade potential and reduced secondary liquidity.
Junior BB notes and equity pieces command wide yield spreads. The equity tranche lacks a fixed coupon rate entirely. Instead, equity distributions depend on residual portfolio interest and trading gains. Equity investors target double-digit internal rates of return to offset first-loss exposure.
Yield spread widening directly affects new issue CLO creation economics. Widening liability spreads squeeze the arbitrage margin for equity investors. When AAA spreads widen significantly, primary market issuance slows rapidly. Conversely, tight AAA spreads spur deal creation across global market centers.
Structural Credit Enhancements and Subordination Buffers
Credit enhancement protects rated debt tranches against underlying loan defaults. Subordination provides the primary form of credit enhancement in CLO structures. It represents the percentage of capital junior to a specific tranche. Higher subordination yields higher credit ratings and lower coupon spreads.
Excess spread provides another vital layer of internal credit protection. Corporate loans in the pool pay higher coupons than the total liability funding costs. This positive yield differential absorbs initial portfolio losses before debt principal vanishes. Unused excess spread flows to equity holders as variable yield.
Overcollateralization buffers provide explicit structural support to rated noteholders. Par value testing ensures collateral amounts consistently exceed outstanding liability balances. Portfolio haircuts apply to lower-rated assets like CCC loans. Excess CCC holdings face mandatory par discount adjustments during calculation cycles.
Reinvestment restrictions protect long-term asset quality within the vehicle. Managers must maintain strict credit diversity, minimum ratings, and weighted average metrics. Non-compliance limits the manager’s ability to trade loans freely. These constraints prevent intentional portfolio risk escalation over time.
Comparing CLO Tranche Risk Profiles and Pricing Factors
Evaluating risk-adjusted returns requires analyzing every layer of the liability structure. Pricing models incorporate default probabilities, recovery rates, and reinvestment assumptions. The table below details structural parameters across typical CLO debt classes.
| Tranche Class | Standard Credit Rating | Typical Subordination Buffer | Primary Risk Metrics | Target Investor Segment |
|---|---|---|---|---|
| Senior Secured | AAA | 35% – 38% | Reinvestment risk, benchmark spread movement | Banks, insurance firms, sovereign wealth funds |
| Senior Mezzanine | AA / A | 20% – 28% | Downgrade risk, modest default exposure | Asset managers, pension funds, global banks |
| Junior Mezzanine | BBB / BB | 9% – 14% | Direct loss exposure, coverage test breach risk | Hedge funds, specialized credit funds, private equity |
| Subordinated Equity | Unrated | 0% (First Loss) | Corporate defaults, severe spread compression | CLO managers, private credit funds, high-yield specialists |
Risk profiles diverge significantly as capital moves down the waterfall ladder. Senior investors prioritize principal preservation and regulatory capital efficiency. Subordinated debt investors seek high current income yields with moderate loss protection. Equity investors take pure entrepreneurial risk on total portfolio performance.
Macroeconomic Drivers of CLO Yield Spread Volatility
Macroeconomic shifts heavily influence secondary market yield spread movements. Federal Reserve monetary policy impacts baseline floating-rate interest metrics directly. Rising interest rates increase debt servicing burdens for leveraged corporate borrowers. Elevated interest costs can lead to deteriorating interest coverage ratios across portfolios.
Corporate default cycles drive credit rating downgrades and spread widening. When portfolio companies suffer cash flow declines, credit metrics deteriorate. Increased migration into CCC rating tiers forces collateral par haircuts. This dynamic triggers coverage test warnings and potential waterfall cash redirections.
Broad market liquidity impacts CLO debt pricing during periods of distress. Institutional investors often sell liquid AAA notes to meet sudden redemptions. Sudden selling pressure broadens AAA yield spreads despite minimal default risk. Secondary market illiquidity can cause disconnects between fundamental risk and market price.
Global economic growth expectations influence underlying borrower loan recovery rates. Higher macroeconomic recovery assumptions tighten yield spreads across junior tranches. Conversely, recession fears expand mezzanine credit spreads significantly. Portfolio managers adjust trading strategies dynamically to navigate evolving market cycles.
Managing Extension and Prepayment Risks in Securitized Credit
Securitized credit instruments exhibit unique structural timing risks. Prepayment risk emerges when corporate borrowers refinance underlying floating-rate loans early. High prepayment volume forces CLO managers to reinvest cash rapidly. Reinvesting in lower-yielding assets reduces total portfolio interest collections over time.
Extension risk occurs during periods of severe macroeconomic loan market stress. Corporate borrowers delay loan refinancing activity when capital markets tighten. The asset pool duration lengthens, keeping CLO liabilities outstanding longer than expected. Investors remain locked into historical coupon spreads during unfavorable market conditions.
Refinancing and reset provisions allow managers to optimize liability pricing dynamics. During tight spread environments, managers can execute debt refinancings seamlessly. A reset extends the transaction’s reinvestment period while repricing all liabilities. These optionalities enhance total returns for equity tranche holders over time.
Understanding tranche capital structures is essential for credit investors. Structural features govern risk allocation, cash priorities, and total return expectations. Analyzing yield spreads requires evaluating collateral performance, structural protections, and macroeconomic conditions simultaneously.
Conclusion
Understanding credit securitization dynamics requires evaluating structural protections alongside market spreads. Collateralized Loan Obligation Tranching effectively segments corporate credit risk for diverse global investors. Senior tranches deliver steady income with exceptional credit safety mechanisms. Junior notes and equity pieces offer elevated yield potential for specialized risk capital.
Continuous monitoring of coverage tests, credit migration, and waterfall dynamics remains critical. Structured credit rewards investors who quantify cash flow mechanics accurately. How will changing interest rate cycles impact your structured credit portfolio allocation strategy?