
Executive Summary
- Asset-Backed Securitization (ABS) structures transform illiquid assets into marketable securities.
- Credit enhancement mechanisms are critical for mitigating risk and attracting diverse investor capital.
- Alternative loan syndication presents unique challenges requiring robust, tailored securitization frameworks.
Deconstructing Asset-Backed Securitization Architectures
Asset-Backed Securitization (ABS) reconfigures traditional lending. It converts illiquid financial assets into tradable securities. This process enhances market liquidity for originators.
The core mechanism involves pooling similar assets. These assets often generate predictable cash flows. Examples include auto loans, credit card receivables, and equipment leases.
A Special Purpose Vehicle (SPV) typically facilitates this transformation. The originator sells the assets to this legally distinct entity. This “true sale” isolates the assets from the originator’s insolvency risk.
Investors then purchase interests in these pooled cash flows. These interests are structured as various tranches. Each tranche carries a distinct risk and return profile. Understanding the architectural nuances is paramount for participants.
The Imperative of Credit Enhancement in ABS Structures
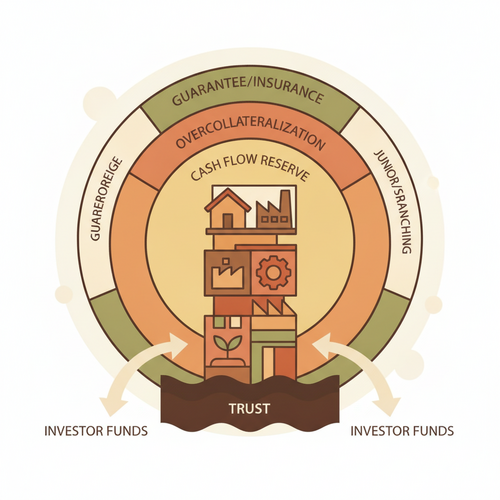
Credit enhancement is not merely an optional feature; it is fundamental. It fortifies the ABS structure against potential losses. This increases investor confidence substantially.
Rating agencies critically evaluate these enhancements. Robust mechanisms often lead to higher credit ratings. Higher ratings reduce funding costs for the securitization issuer.
Credit enhancement mitigates specific risks. These include obligor default, prepayment fluctuations, and servicing interruptions. It safeguards expected cash flow streams for investors.
Without adequate enhancement, securitized products would attract only speculative capital. This limits market depth and efficiency. Enhancements expand the investor base significantly.
Internal Credit Enhancement Mechanisms: Structural Safeguards
Internal enhancements originate within the securitization structure itself. They are integral to the transaction’s design. These mechanisms provide first-line defense against losses.
Subordination and Tranching: The Waterfall Principle
Subordination creates a tiered capital structure. Senior tranches hold priority claim on cash flows. Mezzanine and equity tranches absorb losses first.
This “waterfall” principle directs payments. Senior investors receive principal and interest before junior investors. Junior tranches provide credit support to senior notes.
The equity tranche often bears the initial and highest risk. It offers substantial returns if the underlying assets perform well. This incentivizes rigorous underwriting by the originator.
Overcollateralization (OC): Asset Cushioning
Overcollateralization involves pledging more collateral than the issued security principal. If an ABS pool is worth $110 million, only $100 million in securities might be issued.
This creates an inherent buffer against defaults. A portion of the asset pool can absorb losses. This protects investors in the issued debt tranches.
OC levels are crucial. They reflect the expected loss characteristics of the underlying assets. Higher risk assets typically demand greater overcollateralization.
Excess Spread: Dynamic Loss Absorption
Excess spread is the difference between the interest rate earned on the underlying assets and the interest rate paid to ABS investors plus servicing fees. This difference is held within the SPV.
This surplus cash flow can absorb losses as they occur. It is a dynamic form of credit enhancement. It replenishes credit support over the transaction’s life.
Should losses exceed initial expectations, the excess spread shrinks. This acts as a bellwether for asset performance. It provides ongoing protection for investors.
Reserve Accounts: Liquidity and Loss Support
Reserve accounts are dedicated cash reserves held within the SPV. They serve multiple purposes. These include covering shortfalls in payments or absorbing credit losses.
A cash reserve account provides direct liquidity support. It ensures timely payments to investors. This is critical during periods of stress or unexpected payment delays.
Spread accounts accumulate excess spread over time. These funds can then be used to cover future principal or interest payment shortfalls. They offer a sustained buffer.
Expert Insight: “The interplay of subordination, overcollateralization, and excess spread forms a robust internal defense. Architects of ABS structures meticulously calibrate these layers. This calibration directly impacts perceived credit quality and investor appeal.”
External Credit Enhancement Mechanisms: Third-Party Support
External enhancements involve guarantees from third-party entities. These mechanisms complement internal structures. They often provide additional layers of protection.
Surety Bonds and Guarantees: Monoline Support
Surety bonds involve an insurer guaranteeing performance. If the collateral pool experiences losses, the surety bond issuer compensates investors. This ensures scheduled payments.
Monoline insurance companies historically played a significant role. They issued guarantees on ABS tranches. Their high credit ratings bolstered the ratings of the underlying securities.
These guarantees provide a strong, explicit layer of protection. They transfer credit risk to a highly rated third party. This can significantly reduce investor risk perceptions.
Letters of Credit (LOCs): Bank-Backed Assurance
A Letter of Credit (LOC) is a bank’s commitment. The bank guarantees payment to the ABS trustee or investors. This occurs if certain conditions, like a payment default, are met.
LOCs primarily offer liquidity support. They bridge temporary cash flow shortfalls. They do not necessarily cover principal losses directly, but ensure timely payments.
The credit quality of the issuing bank is paramount. A strong bank rating enhances the credibility of the LOC. This mechanism is particularly useful for short-term liquidity needs.
Swap Agreements: Hedging Market Risks
Swap agreements manage various market risks. Interest rate swaps can convert floating-rate asset income to fixed-rate payments for investors. This mitigates interest rate volatility.
Currency swaps address foreign exchange risk. This is relevant when underlying assets are denominated in different currencies than the ABS securities. They stabilize cash flows.
These agreements are not credit enhancements in the traditional sense. However, they stabilize future cash flows. This indirectly enhances the predictability and safety of payments. They reduce market risk exposure for investors.
Alternative Loan Syndication: A New Frontier for ABS
The landscape of credit is evolving rapidly. Alternative loan syndication, particularly through fintech platforms, is a burgeoning sector. It presents both opportunities and complexities for securitization.
These platforms originate diverse, often granular loans. Examples include small and medium-sized enterprise (SME) loans, consumer installment loans, and even royalty streams. Traditional banks historically underserved these segments.
Securitizing these non-traditional assets requires bespoke architectures. Standardized risk models may not apply directly. Innovative underwriting and servicing frameworks are essential.
The aggregation of these loans into securitizable pools unlocks significant capital. It provides institutional investors access to new asset classes. This diversifies their portfolios.
- SME Loans: Often lack standardized data, requiring advanced analytics.
- Consumer Fintech Loans: Characterized by high volume, short duration, and proprietary scoring models.
- Royalty Securitizations: Cash flows derived from intellectual property, requiring specialized valuation.
Evaluating Credit Enhancement Efficacy in Market Volatility
The true test of credit enhancement lies in its performance during stress. Economic downturns expose weaknesses in structure. Robustness is paramount for sustained investor confidence.
Stress testing methodologies are critical. These simulate severe economic scenarios. They project default rates, recovery rates, and prepayment speeds under duress. This evaluates enhancement adequacy.
Rating agencies employ sophisticated models. They perform extensive surveillance on outstanding ABS transactions. Regular reviews monitor collateral performance and enhancement levels.
In analyzing recent market shifts, structures with dynamic excess spread mechanisms performed well. They adapted to rising delinquencies. Fixed overcollateralization levels required periodic adjustments during extreme events.
Market Warning: “Reliance solely on static credit enhancement can be perilous. Dynamic mechanisms that adjust to evolving collateral performance are increasingly preferred. Continuous monitoring is non-negotiable for mitigating tail risks.”
Regulatory Scrutiny and Evolution of ABS Standards
The 2008 financial crisis highlighted vulnerabilities in securitization. Subsequent regulatory reforms significantly reshaped the ABS market. These aimed to increase transparency and accountability.
The Dodd-Frank Act introduced stringent requirements in the U.S. It mandated risk retention rules. This requires originators or sponsors to hold a portion of the securitized debt.
Risk retention aligns incentives. It ensures originators have “skin in the game.” This discourages the securitization of poorly underwritten loans. It enhances overall asset quality.
Basel III implications also affect banks participating in securitization. Higher capital requirements for certain exposures influence their involvement. This impacts market liquidity and structure.
The regulatory landscape continues to evolve globally. Regulators seek a balance. They aim to foster capital formation while safeguarding financial system stability. Continuous adaptation is necessary.
For more detailed insights on risk retention, consult official regulatory guidelines or resources like Investopedia’s Asset-Backed Security definition. Further information on credit enhancement can be found at Investopedia’s Credit Enhancement article.
Conclusion
Asset-Backed Securitization architectures are complex financial instruments. Their efficacy hinges on meticulously designed credit enhancement mechanisms. These safeguards protect investors from diverse risks.
Both internal and external enhancements play vital roles. They underpin the integrity and viability of securitized products. Understanding their nuanced application is critical.
The rise of alternative loan syndication demands adaptable frameworks. Innovation in structuring these novel asset classes is paramount. Robust enhancement ensures their integration into capital markets.
Ongoing market surveillance and regulatory compliance are non-negotiable. These ensure the resilience of ABS structures. How will evolving economic landscapes continue to challenge and refine these essential credit enhancement strategies?