
Executive Summary
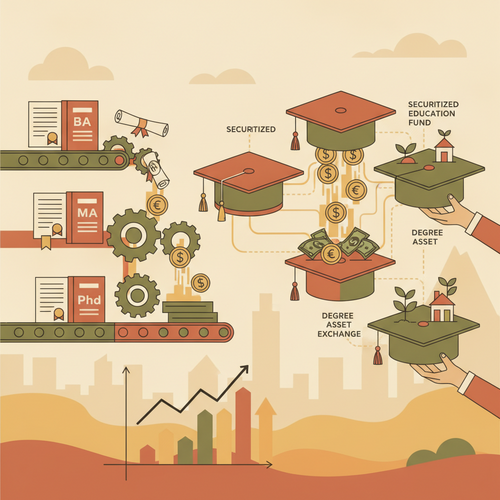
- Income Share Agreement (ISA) securitization converts future postgraduate income streams into investment-grade assets.
- This innovative financial instrument facilitates significant institutional capital deployment into human capital development.
- It offers diversified investment opportunities while addressing crucial educational funding gaps.
Understanding Income Share Agreements (ISAs)
Income Share Agreements represent a contractual arrangement. A student receives educational funding in exchange for a percentage of their future income. This payment obligation typically activates only upon earning above a specified income threshold. ISAs align the financial interests of students and their funding providers. Success for one directly benefits the other. This model mitigates upfront tuition costs for participants.
Defining the ISA Model
The core ISA premise is income-contingent repayment. Unlike traditional debt, ISA payments fluctuate with individual earnings. If a participant’s income falls, their payments decrease or pause entirely. A payment cap limits the total amount repayable. A fixed payment term also typically applies. These features provide a financial safety net for graduates. This structure distinguishes ISAs from conventional lending products.
Key Differences from Traditional Student Loans
Traditional student loans accrue interest regardless of income. Repayment schedules are often rigid. Default risks are substantial for unemployed or underemployed graduates. ISAs, conversely, lack an interest rate. Instead, they specify an “income share percentage.” They feature an “income floor” and a “payment cap.” This structural difference fundamentally shifts risk away from the borrower. It fosters greater financial resilience among postgraduate recipients. Loans create fixed obligations. ISAs create variable commitments. This flexibility is a critical differentiator. It makes ISAs a more adaptable financing solution.
The Mechanics of ISA Securitization
Securitization transforms a pool of individual ISA contracts into marketable securities. This process allows originators to offload risk and inject fresh capital. It expands their capacity to fund more students. Institutional investors gain access to a new asset class. These assets are tied to human capital performance. The process involves several complex financial engineering steps. It creates liquid instruments from illiquid assets.
Structuring ISA Pools
ISA pools aggregate numerous individual agreements. Diversification is key at this stage. Factors like academic program, institution, geography, and expected income trajectories are considered. This aggregation reduces idiosyncratic risk. Statistical modeling predicts the aggregate income stream. A well-constructed pool forms the basis for a robust securitization. Pool quality directly impacts investor confidence. It influences the subsequent credit ratings.
Tranching and Credit Enhancement Strategies
ISA securitization often involves tranching. The pooled cash flows are divided into different tranches. Each tranche carries a distinct risk and return profile. Senior tranches typically offer lower yields but higher credit protection. Subordinated tranches absorb initial losses. They offer higher potential returns. Credit enhancement mechanisms further bolster investor confidence. These include overcollateralization, reserve accounts, and third-party guarantees. These strategies reduce perceived investment risk. They broaden the appeal to diverse institutional investors. Structured finance techniques are critical here. They ensure stability across varying market conditions.
The Role of Special Purpose Vehicles (SPVs)
A Special Purpose Vehicle (SPV) is central to securitization. The ISA contracts are transferred from the originator to the SPV. This legal separation isolates the assets from the originator’s balance sheet risk. The SPV then issues securities backed by these assets. Investors purchase these securities. The cash flows from the ISA pool repay the SPV’s obligations. This bankruptcy-remote structure protects investors. It shields them from the originator’s financial distress. The SPV facilitates efficient capital market access. It maintains the integrity of the securitized assets.
Expert Insight: “Effective ISA securitization hinges on meticulous underwriting and robust legal frameworks. Institutional appetite for this asset class is growing, driven by diversification benefits and favorable economic alignment.”
Institutional Investor Perspectives and Due Diligence
Institutional investors approach ISA securitization with rigorous due diligence. They seek assets offering compelling risk-adjusted returns. ISAs provide exposure to human capital, a distinct economic driver. This differentiates them from traditional fixed-income securities. The long-term income-contingent nature requires sophisticated analysis. Investors must understand the underlying cohort performance. They evaluate the originator’s underwriting capabilities. Asset-liability matching strategies are crucial for portfolio managers.
Attractive Risk-Adjusted Returns
ISA-backed securities can offer attractive yields. These often exceed those of comparable duration fixed-income instruments. The income-contingent structure hedges against recessionary impacts on borrowers. This intrinsic feature provides a degree of downside protection. Such characteristics are appealing in volatile market environments. They contribute to a favorable risk-adjusted return profile. Investors assess these returns against expected economic cycles. They consider the stability of future income streams.
Assessing Human Capital Risk
Evaluating human capital risk is paramount. This involves analyzing the educational programs funded. Graduate employment rates, earning potential, and industry demand are key metrics. The originator’s selection process for ISA recipients is also scrutinized. Diversification across various programs and demographics mitigates concentration risk. Predictive models forecast income trajectories. These models inform expected repayment performance. Robust data analytics are indispensable for this assessment. They quantify the probability of repayment success.
Portfolio Diversification Benefits
ISA securitization offers significant diversification benefits. It introduces a revenue stream less correlated with traditional market cycles. Returns are tied to individual economic productivity. This contrasts with corporate or sovereign debt. Adding ISA-backed securities can reduce overall portfolio volatility. It enhances portfolio resilience. This unique correlation profile is highly valued. It strengthens asset allocation strategies for large institutional funds. Pension funds and endowments find this particularly attractive. They seek stable, long-term growth assets.
Risk Mitigation and Performance Analytics in ISA Portfolios
Managing risk in ISA portfolios demands sophisticated strategies. Originators and servicers implement stringent protocols. These span from initial underwriting to ongoing performance monitoring. Data-driven analytics are critical. They inform decision-making throughout the asset lifecycle. Proactive risk mitigation enhances investor confidence. It ensures the long-term viability of ISA securitization.
Underwriting and Origination Protocols
Effective underwriting is foundational. It involves rigorous assessment of applicant aptitude and program quality. Predicting future earnings potential is key. This considers career placement rates and industry outlook. Strict origination protocols ensure compliant and robust contracts. These minimize adverse selection. They maximize the likelihood of successful repayment. Transparent criteria build trust. They contribute to a high-quality asset pool. Strong underwriting reduces default probabilities. It enhances the intrinsic value of the ISA portfolio.
Advanced Predictive Modeling
Advanced predictive analytics are indispensable. Machine learning models forecast graduate income trajectories. They assess the probability of hitting income thresholds. These models also predict prepayment behavior or deferred payments. Real-time data feeds continuously refine these predictions. Granular insights into cohort performance are generated. This sophisticated modeling optimizes portfolio management. It informs pricing and risk adjustments for future securitizations. Data science drives efficient capital allocation.
Servicing and Collection Efficiencies
Efficient servicing is vital for performance. This includes proactive communication with ISA participants. Transparent payment processing is essential. Flexible support during income fluctuations maintains engagement. Collection strategies are tailored to the income-contingent nature. They differ significantly from traditional debt collection. Focus remains on supporting participant success. This approach fosters higher repayment rates. It preserves the value of the securitized assets. Advanced platforms automate many servicing functions.
Regulatory Frameworks and Compliance Challenges
The regulatory landscape for ISAs is evolving. Securitization adds layers of complexity. Navigating diverse legal interpretations is crucial. Ensuring compliance with consumer protection laws is paramount. The novelty of the asset class requires careful legal structuring. Transparency remains a significant challenge. Regulatory clarity is vital for market maturation. Consistent frameworks will foster broader adoption.
Navigating Securities Law Implications
ISA-backed securities must comply with established securities laws. Classification as a security triggers disclosure requirements. Registration with regulatory bodies may be necessary. The structure of the securitization affects legal treatment. Clear legal opinions are essential. They confirm compliance with federal and state regulations. Missteps can lead to significant penalties. They can also undermine investor trust. Legal counsel specializing in structured finance is indispensable.
Consumer Protection Considerations
Consumer protection is a central concern for ISAs. Fair disclosure of terms is critical. Avoiding predatory practices is paramount. Clear communication about income floors and caps is necessary. Regulators scrutinize potential for overpayment or unclear obligations. The income-contingent nature offers inherent protections. However, robust oversight prevents misuse. Adherence to consumer finance regulations builds market legitimacy. It safeguards participant welfare. Ethical structuring underpins long-term success.
Transparency and Disclosure Requirements
Transparency is a cornerstone of investor confidence. Clear disclosure of underlying ISA pool characteristics is mandatory. Information on performance metrics must be readily available. Details on underwriting standards and servicing practices are crucial. Investors demand comprehensive reporting. This includes delinquency rates and income attainment data. Regulatory bodies emphasize robust disclosure. They ensure investors can make informed decisions. Openness fosters a healthy, liquid secondary market.
Economic Impact and Human Capital Development
ISA securitization extends beyond financial engineering. It profoundly impacts human capital development. It unlocks funding for critical skills training. This fuels economic growth. The model aligns educational outcomes with financial returns. It incentivizes quality education. The broader macroeconomic benefits are substantial.
Expanding Access to Education
ISAs democratize access to high-quality education. They reduce financial barriers for aspiring students. This is particularly true for postgraduate and vocational programs. Individuals from diverse socioeconomic backgrounds benefit. They can pursue opportunities previously out of reach. This expands the talent pool. It promotes social mobility. Educational access is a powerful economic multiplier. Securitization scales this access significantly.
Aligning Incentives: Student Success and Investor Returns
The ISA model inherently aligns incentives. Investors profit only when students succeed professionally. This motivates originators to select promising students. It encourages support services post-graduation. Educational institutions are incentivized to deliver effective programs. Their reputation directly impacts ISA pool performance. This symbiotic relationship fosters a robust educational ecosystem. It creates a virtuous cycle of investment and achievement.
Macroeconomic Implications for Workforce Development
ISA securitization addresses critical workforce skill gaps. It channels capital into high-demand fields. This enhances national competitiveness. A better-educated workforce drives innovation and productivity. It reduces unemployment and boosts GDP. The flexible financing model adapts to evolving labor market needs. It supports continuous upskilling and reskilling initiatives. This contributes to a dynamic and resilient economy.
Market Warning: “While promising, the long-term macroeconomic impacts of large-scale ISA securitization require careful monitoring. Potential systemic risks, though currently low, must be continuously assessed.”
Emerging Trends and Future Outlook for ISA Securitization
The ISA securitization market is still nascent. However, several trends signal significant future growth. Technological advancements are streamlining operations. The expansion of alternative education models creates new opportunities. Global markets are also exploring similar structures. This asset class is poised for substantial evolution. It will become a more prominent feature in institutional portfolios.
Technological Innovations in ISA Platforms
Fintech innovations are transforming ISA origination and servicing. AI-powered underwriting models enhance risk assessment. Blockchain technology could improve transparency and transaction efficiency. Digital platforms streamline application processes and payment collection. These technological advancements reduce operational costs. They enhance scalability and accuracy. This makes ISAs more attractive for both students and investors. Automated processes improve overall market efficiency.
Growth of the Alternative Education Market
The rise of coding bootcamps, vocational training, and certificate programs fuels ISA growth. These alternative education providers often rely heavily on ISAs. They offer rapid reskilling pathways. This meets immediate industry demands. Securitization provides these institutions with vital funding. It supports their expansion. This market segment is growing rapidly. It represents a significant opportunity for ISA-backed securities. It diversifies the underlying asset base.
Global Market Expansion Potential
The ISA model is gaining traction beyond North America. Countries are exploring similar income-contingent financing solutions. This addresses their unique educational and workforce challenges. Global expansion of ISA securitization could follow. Different regulatory environments will require adaptation. However, the core benefits remain universal. International investors may soon gain access to these diverse human capital assets. This promises substantial long-term market growth.
Strategic Implementation for Educational Institutions and Fund Managers
Successful engagement with ISA securitization demands strategic foresight. Educational institutions must optimize their ISA programs. Fund managers require sophisticated investment strategies. Building robust infrastructure is paramount. This ensures efficient and compliant operations. It maximizes value for all stakeholders.
Optimizing ISA Program Design
Educational institutions must design ISAs strategically. This involves setting appropriate income shares and caps. Aligning terms with program outcomes is essential. Clear communication with students builds trust. A strong track record of graduate success attracts capital. Institutions should continuously evaluate program effectiveness. This optimization enhances the quality of securitized pools. It ensures a sustainable funding model.
Attracting Institutional Capital
Originators must present a compelling case to investors. This includes transparent data on past performance. A clear narrative on risk mitigation is vital. Partnering with experienced financial advisors is beneficial. Demonstrating robust compliance frameworks is non-negotiable. Building long-term relationships with anchor investors is key. This proactive engagement facilitates successful securitizations. It secures consistent funding streams.
Building Robust Servicing Infrastructure
A scalable and compliant servicing infrastructure is critical. This includes advanced payment processing systems. Robust customer support channels are necessary. Comprehensive data management and reporting capabilities are essential. Compliance with all consumer protection laws is paramount. Outsourcing to specialized servicers can be an option. This infrastructure ensures efficient collection. It maintains positive participant relationships. It protects investor returns.
Conclusion
Income Share Agreement securitization represents a transformative development. It bridges the gap between human capital investment and institutional finance. This innovative mechanism unlocks significant capital. It supports postgraduate education and workforce development. Investors gain access to a unique, diversified asset class. Challenges remain in regulation and market standardization. However, the foundational benefits are compelling. Continued market evolution will enhance liquidity and appeal. How will this instrument reshape the future of educational finance globally?