
Executive Summary
- Charitable Remainder Unitrusts (CRUTs) strategically defer capital gains taxes.
- They enhance liquidity for high-net-worth individuals through annuitized income.
- CRUTs offer significant estate planning and philanthropic advantages.
Understanding the Charitable Remainder Unitrust (CRUT) Mechanism
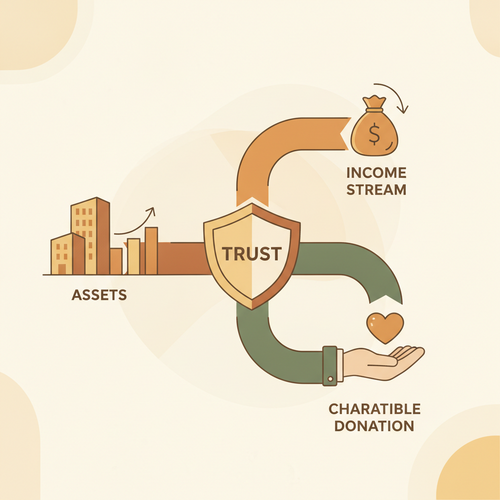
A Charitable Remainder Unitrust (CRUT) stands as an irrevocable trust instrument. It permits high-net-worth donors to convert highly appreciated, illiquid assets into a lifetime income stream. Simultaneously, it designates a charitable organization as the ultimate remainder beneficiary.
Upon asset contribution, the trust sells these assets without immediate capital gains taxation. The proceeds are then reinvested. This structure allows for a diversified portfolio and ongoing growth potential.
The donor, or another non-charitable beneficiary, receives a variable income payment annually. This payment is a fixed percentage of the trust’s fair market value, revalued annually. This unitrust amount distinguishes it from fixed annuity payments.
The trust’s irrevocability is a cornerstone. Once assets are transferred, the donor relinquishes control over them. This commitment is fundamental to its tax-advantaged status.
Core Functionality and Irrevocability
The CRUT’s core functionality centers on asset transformation. Illiquid assets, such as real estate or private stock, become liquid, income-producing investments. This facilitates diversification without triggering an immediate taxable event.
Irrevocability means the trust terms cannot be altered. The assets are permanently removed from the donor’s taxable estate. This ensures the charitable intent is fulfilled.
Income Beneficiary Versus Remainder Beneficiary Roles
The income beneficiary receives the periodic payments. This is typically the donor or their designated heirs. These payments continue for a specified term, often the beneficiary’s lifetime or a maximum of 20 years.
The remainder beneficiary is a qualified charitable organization. This entity receives the trust’s remaining assets after the income period concludes. This dual structure supports both personal financial goals and philanthropic endeavors.
Strategic Capital Gains Deferral Through CRUTs
One of the most compelling advantages of a CRUT is its ability to defer capital gains taxes. Donors contribute appreciated assets to the trust. The trust then sells these assets. This sale occurs without incurring immediate capital gains liability for the donor.
The trust itself is tax-exempt. This enables the full value of the appreciated assets to be reinvested. This allows for significantly greater growth potential over time. This mechanism contrasts sharply with a direct sale by the individual, which triggers immediate taxation.
Avoiding Immediate Taxable Events
When highly appreciated assets are sold directly, capital gains taxes are instantly due. This reduces the investable principal. A CRUT bypasses this immediate reduction.
The trust liquidates the assets tax-free. This preserves the entire asset value for reinvestment. This deferral acts as a powerful wealth accumulation strategy.
Diversification of Concentrated Highly Appreciated Assets
High-net-worth estates often hold concentrated positions. These might include founder’s stock or legacy real estate. These assets often carry a low-cost basis.
A CRUT allows for the divestiture of these positions without punitive taxation. The trust can diversify the portfolio. This reduces risk concentration and enhances long-term stability.
Reinvestment of Untaxed Capital for Enhanced Growth
The full, untaxed proceeds from the asset sale are reinvested within the CRUT. This larger principal generates higher potential returns. This compounding effect significantly enhances wealth preservation.
From an operational standpoint, this means more capital is working for the beneficiaries. It maximizes the value available for both income payments and the ultimate charitable gift.
Enhancing Liquidity and Income Streams for High-Net-Worth Individuals
CRUTs provide a consistent, variable income stream. This significantly enhances liquidity for donors. Especially beneficial for those holding illiquid, high-value assets. These assets might otherwise be difficult to convert into spendable income.
The annual revaluation of the trust assets determines the payout. This allows for income payments to potentially grow over time. This feature provides a hedge against inflation. It offers long-term financial security.
Annuitized Distributions and Flexible Payout Rates
Beneficiaries receive annual payments based on a set percentage. This percentage is typically between 5% and 50% of the trust’s fair market value. The rate is established at the trust’s inception.
This flexibility allows for tailored income planning. It balances immediate income needs with the eventual charitable contribution. Careful selection of the payout rate is critical for trust longevity.
Types of CRUTs: Standard, Net Income, and Flip Variants
- Standard CRUT (SCRUT): Pays a fixed percentage of the trust’s value annually. Distributions occur regardless of trust income.
- Net Income CRUT (NICRUT): Pays the lesser of the fixed percentage or the actual net income earned. This is suitable for assets that may not generate substantial income immediately.
- Net Income with Makeup CRUT (NIMCRUT): Similar to NICRUT but includes a “makeup” provision. Deficiencies from prior years can be paid in later years when income exceeds the payout percentage.
- Flip CRUT: Starts as a NICRUT or NIMCRUT. It “flips” to a Standard CRUT upon a specific event. This is often the sale of an illiquid asset. This structure addresses initial illiquidity challenges.
Choosing the appropriate CRUT type depends on the donor’s asset profile. It also depends on their income needs and timeline for asset liquidation. Each variant offers distinct advantages.
Expert Insight: “In analyzing recent market shifts, we observe an increasing preference for Flip CRUTs among entrepreneurs. This allows them to contribute private company stock, deferring income until a liquidity event occurs.”
Taxation and Philanthropic Advantages
The tax benefits associated with CRUTs extend beyond capital gains deferral. Donors also receive a significant charitable income tax deduction. This deduction is calculated based on the present value of the future remainder interest. This reduces current taxable income.
Furthermore, CRUTs remove assets from the donor’s estate. This effectively reduces potential estate taxes. This dual benefit makes them powerful tools for wealth transfer and philanthropic giving.
Charitable Income Tax Deduction
The present value of the charitable remainder interest qualifies for an income tax deduction. This deduction is available in the year of the trust’s funding. The specific amount depends on the payout rate, beneficiary ages, and IRS actuarial tables.
This immediate tax benefit can be substantial. It helps offset other taxable income. The deduction limits typically follow standard charitable contribution rules.
Estate Tax Reduction and Unified Credit Implications
Assets transferred to a CRUT are removed from the donor’s gross estate. This significantly reduces the taxable estate. This strategy minimizes potential estate tax liabilities.
It also effectively preserves the donor’s unified credit for other assets. This facilitates a more efficient intergenerational wealth transfer strategy. It aligns with broader estate planning objectives.
Fulfilling Philanthropic Intentions with Greater Impact
CRUTs empower donors to make substantial charitable gifts. These gifts are often larger than direct donations. The tax-free growth within the trust increases the ultimate remainder value.
This structure ensures a lasting legacy. It supports favored causes while providing personal financial benefits. It represents a strategic convergence of personal finance and altruism.
Operational Considerations and Fiduciary Responsibilities
Establishing and managing a CRUT involves significant operational responsibilities. Proper trust administration is paramount for compliance and performance. This includes meticulous record-keeping and adherence to IRS regulations.
Selecting a qualified trustee is a critical decision. The trustee bears fiduciary duties. They must manage investments prudently and distribute income correctly. Errors can lead to adverse tax consequences.
Trust Administration and Investment Management
The trustee is responsible for all aspects of trust administration. This includes asset custody, investment management, and calculating annual payout amounts. They must ensure the trust adheres to its governing instrument.
Investment decisions within the CRUT must align with its long-term goals. Balancing income generation for beneficiaries with preserving the remainder for charity is crucial. This requires sophisticated financial acumen.
Choosing a Qualified and Experienced Trustee
The trustee can be an individual, a corporate trustee, or a charitable organization. An independent, professional trustee is often recommended. They bring impartiality and specialized expertise.
Their role includes navigating complex tax rules. They ensure timely filing of tax returns (Form 5227, Form 1041-A). Their experience minimizes compliance risks.
Compliance with IRS Regulations and Payout Requirements
CRUTs must strictly comply with IRC Section 664. Failure to do so can jeopardize the trust’s tax-exempt status. This includes adherence to the minimum 5% and maximum 50% payout rates.
The remainder interest must also be at least 10% of the initial contribution. Regular valuations and accurate calculations are mandatory. These ensure continuous regulatory compliance.
Advanced Wealth Planning: Integrating CRUTs into a Comprehensive Strategy
CRUTs are not isolated financial instruments. They integrate seamlessly into broader wealth planning architectures. They complement other sophisticated strategies. This includes family foundations and donor-advised funds.
Their flexibility makes them valuable for succession planning. They also assist in intergenerational wealth transfer. They address complex legacy goals for ultra-high-net-worth families.
Synergy with Donor-Advised Funds and Private Foundations
A CRUT can terminate into a donor-advised fund (DAF) or private foundation. This provides continued philanthropic control to the donor’s family. It extends the impact of the charitable gift.
This combination offers immediate tax benefits from the CRUT. It also allows for flexible, long-term grant-making. It represents a robust philanthropic giving strategy.
Succession Planning and Intergenerational Wealth Transfer
CRUTs facilitate orderly asset transfer. They provide income for surviving family members. The charitable remainder bypasses estate taxation.
This helps preserve family wealth. It aligns family values with philanthropic objectives. It is a cornerstone of thoughtful legacy planning.
Mitigating Generation-Skipping Transfer Tax (GSTT)
For some complex estate plans, CRUTs can help mitigate the Generation-Skipping Transfer Tax (GSTT). By directing assets to charity, the trust structure can reduce exposure to this tax.
This is particularly relevant when assets would otherwise pass to grandchildren or further generations. Expert legal and tax advice is crucial here. Navigating GSTT rules is intricate.
Common Pitfalls and Due Diligence
While advantageous, CRUTs require careful consideration. Their irrevocable nature demands foresight. Donors surrender control over the contributed assets permanently.
Potential pitfalls include complex administration and strict regulatory compliance. Due diligence is essential before implementation. A thorough understanding prevents future complications.
Irrevocable Nature and Loss of Control
The decision to fund a CRUT is permanent. Assets cannot be retrieved once transferred. This loss of direct control must be fully understood by the donor.
This permanence is necessary for the tax benefits. It underscores the need for careful planning. Ensure liquidity needs are met outside of the trust.
Minimum Charitable Remainder Value Requirements
IRS regulations mandate that the charitable remainder interest must be at least 10% of the initial fair market value. If the payout rate is too high or beneficiaries are too young, this minimum might not be met.
This requirement ensures genuine charitable intent. It affects the design of the payout schedule. Proper actuarial calculations are essential.
The Indispensable Role of a Professional Advisory Team
Establishing a CRUT necessitates a team of specialized advisors. This includes estate planning attorneys, tax professionals, and financial advisors. Their expertise ensures optimal structure and compliance.
Navigating the legal, tax, and investment intricacies is complex. A coordinated professional approach minimizes risks. It maximizes the financial and philanthropic impact.
Market Warning: “From an operational standpoint, underestimating the fiduciary responsibilities or failing to engage experienced counsel for CRUT administration can lead to severe IRS penalties and erosion of trust benefits.”
Conclusion
Charitable Remainder Unitrusts present a sophisticated strategy. They allow high-net-worth individuals to defer capital gains. Enhance personal liquidity. They also fulfill significant philanthropic goals. The tax advantages are substantial. The planning intricacies demand expert guidance. Proper implementation unlocks significant wealth optimization. Are you strategically positioning your estate for maximum impact and legacy?