
Executive Summary
- Commercial Real Estate (CRE) mezzanine debt occupies a critical position within the capital stack.
- It offers investors enhanced yield opportunities, balancing risk and subordinated positioning.
- Effective subordinated debt engineering is paramount for maximizing returns and mitigating inherent risks.
Understanding the CRE Capital Stack: A Foundational Review
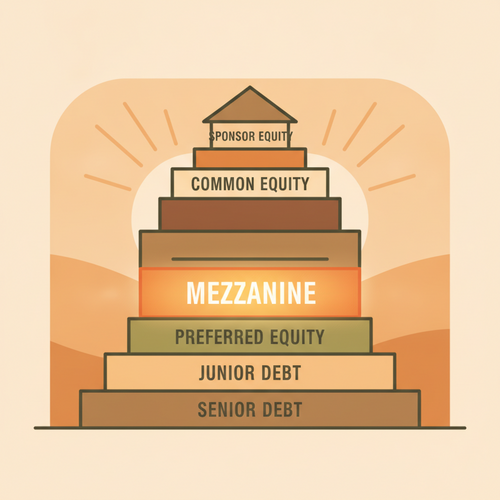
The commercial real estate capital stack represents a hierarchical structure. It delineates the various forms of financing applied to a property. Each layer possesses distinct risk, return, and priority characteristics. Understanding this framework is fundamental for sophisticated investors.
Senior debt forms the base, holding the highest claim on assets. It provides the lowest risk-adjusted return. Equity, whether preferred or common, sits at the top. This position carries the highest risk but offers the greatest potential for upside appreciation.
The layers include senior secured debt, mezzanine debt, preferred equity, and common equity. Each tranche plays a specific role. They facilitate a project’s funding and dictate creditor priorities. Strategic placement within this stack defines an investment’s profile.
The Nuances of Mezzanine Tranches in CRE Financing
Mezzanine debt is a hybrid form of financing. It blends characteristics of both debt and equity. It sits below senior debt but above sponsor equity or preferred equity. This placement allows for higher leverage than senior debt alone.
This debt typically carries a higher interest rate than senior secured loans. It compensates lenders for its subordinate position. Mezzanine loans often feature an equity kicker. This provides an additional return beyond the fixed coupon payment. Warrants or profit participation enhance investor yield.
Loan-to-value (LTV) ratios for mezzanine tranches generally range from 70% to 85%. This fills a crucial gap in financing. It allows sponsors to reduce their required equity contribution. The mezzanine finance structure is inherently flexible. It can be tailored to specific deal requirements and market conditions.
Expert Insight: “Seasoned capital allocators recognize mezzanine debt’s role. It significantly enhances leverage. It simultaneously optimizes equity returns in value-add or opportunistic CRE strategies. Proper due diligence on the sponsor and asset is non-negotiable.”
Yield Maximization Strategies for Mezzanine Investors
Mezzanine investors target superior risk-adjusted returns. Their yield maximization strategies are multi-faceted. They leverage both fixed income and equity-like components. This approach capitalizes on the debt’s unique structural attributes.
Higher coupon rates are a primary driver of yield. These rates reflect the increased risk of subordination. Many mezzanine structures incorporate a payment-in-kind (PIK) component. PIK interest accrues and is added to the principal balance. This defers cash payments, benefiting sponsors. It boosts the lender’s effective yield over the loan term.
Equity participation is another powerful yield enhancer. Warrants grant the right to purchase sponsor equity at a predetermined price. Profit-sharing agreements provide a direct stake in property appreciation. These equity kickers can significantly amplify total returns. They align investor interests with the project’s success.
- **Increased Coupon Rates:** Direct compensation for elevated risk exposure.
- **Payment-in-Kind (PIK) Interest:** Deferral of cash payments, compounding returns.
- **Equity Warrants:** Potential for significant upside participation in the property’s value.
- **Exit Fees and Origination Fees:** Upfront and backend charges boosting overall yield.
- **Prepayment Premiums:** Penalties for early repayment, securing expected returns.
Engineering Subordinated Debt: Key Structural Considerations
The effective engineering of subordinated debt requires meticulous attention. Legal and financial structures define its risk profile. An intercreditor agreement is paramount. This document governs the rights and remedies of all lenders. It establishes clear rules for payment priority and foreclosure.
Collateral for mezzanine loans is typically a pledge of the sponsor’s equity. This means the lender has a security interest in the ownership entity. It does not directly collateralize the real estate asset. This mechanism allows a quick foreclosure on the equity. The mezzanine lender can then step into the sponsor’s shoes. They assume control of the property.
Payment waterfalls dictate cash flow distribution. They ensure senior debt is paid first. Only then does the mezzanine tranche receive its payments. Default provisions outline specific events triggering lender remedies. Cure periods offer the borrower a chance to rectify breaches. These legal intricacies are vital for protecting the mezzanine position.
| Feature | Senior Debt | Mezzanine Debt |
|---|---|---|
| **Collateral** | Real Estate Asset | Pledge of Equity (LLC/Partnership Interests) |
| **Priority** | First Lien | Subordinate to Senior Debt, Senior to Equity |
| **LTV Range** | 50% – 70% | 70% – 85% (Blended) |
| **Remedy** | Mortgage Foreclosure | UCC Foreclosure on Equity |
| **Typical Rate** | Lower (e.g., SOFR + 200-350 bps) | Higher (e.g., SOFR + 500-1000 bps + equity) |
Risk Mitigation in Mezzanine Investments: A Sponsor’s Perspective
Sponsors engaging mezzanine capital must meticulously manage inherent risks. While offering leverage, it introduces complexity. Robust due diligence is the first line of defense. This encompasses market analysis, property valuation, and sponsor track record assessment.
Conservative underwriting assumptions are critical. Stress-testing cash flows under various scenarios reveals potential vulnerabilities. This includes adverse interest rate shifts or vacancy spikes. A strong intercreditor agreement clearly defines responsibilities. It outlines rights during periods of financial distress. This minimizes ambiguity and disputes.
Alignment of interests between sponsor and lender is crucial. A substantial sponsor equity contribution demonstrates commitment. It reduces moral hazard. Contingency planning for potential defaults is also prudent. Understanding cure rights and lender remedies prevents unexpected loss of control. Effective communication channels between all capital partners mitigate issues proactively.
Market Warning: “The illiquidity of mezzanine tranches demands a long-term perspective. Exit strategies must be clearly defined. Re-leverage risk and the potential for capital stack ‘cram-downs’ are significant considerations during market downturns. Prudent management is paramount.”
Market Dynamics and Macroeconomic Impacts on Mezzanine Capital
The supply and demand for mezzanine capital fluctuate with market cycles. Macroeconomic factors exert considerable influence. Interest rate environments directly affect pricing. Rising rates can compress spreads on senior debt. This often pushes more borrowers towards hybrid solutions like mezzanine.
Economic growth fosters development and acquisition activity. This increases demand for all forms of capital. Conversely, recessions heighten risk aversion. Lenders become more conservative. This can reduce mezzanine availability and increase pricing. Regulatory changes, while less direct, can also impact capital flow.
Emerging trends further shape the mezzanine landscape. Environmental, Social, and Governance (ESG) factors gain prominence. Investors increasingly scrutinize a property’s sustainability profile. Technological advancements in proptech also influence asset values. These elements integrate into sophisticated underwriting models. They affect perceived risk and required yields.
Conclusion
Commercial real estate mezzanine tranches are indispensable. They optimize capital structures. They provide critical financing flexibility. Investors achieve superior risk-adjusted returns through strategic engineering. Careful analysis of subordination, intercreditor agreements, and equity participation is essential. Success hinges on a deep understanding of market dynamics. It also requires meticulous risk mitigation. How will your next CRE venture leverage this powerful financing tool?