
Executive Summary
- Quantitative tightening (QT) directly contracts bank reserves, driving up corporate risk premiums across all credit tiers.
- Investment-grade bonds face moderate yield adjustments, while high-yield corporate debt encounters severe refinancing hurdles.
- Institutional investors must adjust duration strategies to mitigate liquidity friction and term premium expansion.
The Mechanics of Quantitative Tightening and Balance Sheet Runoff
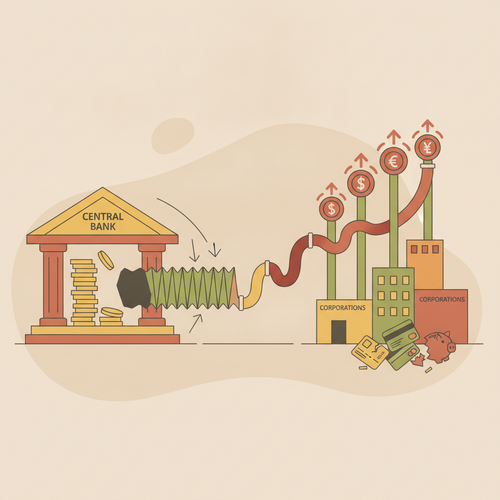
Central banks continue to shrink their balance sheets. This policy process is known as quantitative tightening. Central banks allow sovereign bonds to mature without full reinvestment. Consequently, market liquidity contracts steadily.
Reserve balances at commercial banks decline during balance sheet runoff. This withdrawal creates structural shifts in institutional asset pricing. Term premiums rise as sovereign debt supply increases. Sovereign bond yields set the benchmark for corporate credit.
The Federal Reserve and European Central Bank drive this monetary contraction. Their System Open Market Account portfolios continue to shrink. Passive runoff removes a major price-insensitive buyer from sovereign debt markets. Private capital must step in to absorb excess market supply.
As a result, market clearing prices require higher overall yields. Corporate issuers must offer larger yield coupons to attract institutional capital. You can learn more about balance sheet contraction dynamics on Investopedia’s Quantitative Tightening overview.
Transmission Channels to Corporate Bond Markets
Quantitative tightening impacts corporate debt through distinct economic channels. The primary mechanism is the direct risk-free benchmark channel. When sovereign yields increase, corporate debt yields must follow immediately.
The secondary channel involves liquidity premium expansion. Central bank contraction drains systemic cash buffers. Secondary market corporate bond trading becomes more expensive. Bid-ask spreads widen, reflecting higher execution risk for dealer desks.
The third channel is supply crowding. Sovereign treasuries issue record amounts of debt to cover fiscal deficits. Sovereign paper competes directly with corporate debt for investor capital. Risk-averse institutions often choose risk-free government securities over corporate paper.
Corporate CFOs face higher marginal borrowing costs across all tenors. Floating-rate debt holders experience immediate interest coverage compression. Fixed-rate debt issuers face elevated yields when refinancing mature paper. Capital structures require urgent risk reassessments.
Investment Grade vs. High Yield Spread Trajectories
Credit spreads behave differently across rating spectrums during monetary contraction. Investment Grade (IG) issuers exhibit relative resilience. High Yield (HY) issuers encounter severe credit friction.
IG balance sheets generally maintain strong cash reserves. These corporations locked in long-term low coupon rates prior to policy tightening. However, BBB-rated debt sits at risk of downgrade. Downgrades trigger forced sales by mandate-constrained institutional funds.
High yield corporate debt exhibits high sensitivity to tight monetary conditions. Speculative-grade issuers rely heavily on short-term debt and bank syndication. Interest coverage ratios degrade rapidly as refinancing rates rise. Default probabilities escalate for lower-tier issuers.
| Metric / Indicator | Investment Grade (IG) Debt | High Yield (HY) Debt |
|---|---|---|
| Average Yield Sensitivity | Moderate (Driven by Benchmark Rates) | High (Driven by Credit Spreads) |
| Refinancing Risk Exposure | Low to Moderate (Longer Maturity Walls) | Severe (Short Maturity Profiles) |
| Liquidity Premium Expansion | Tight Spreads, Stable Depth | Wide Spreads, Fragmented Liquidity |
| Default Rate Projections | Historically Below 0.5% | Projected 4.5% – 6.0% under Prolonged QT |
| Primary Investor Base | Pension Funds, Insurers, Sovereign Wealth | Hedge Funds, Private Credit, Retail Funds |
Refinancing Walls and Maturity Schedule Vulnerabilities
Corporations face a massive refinancing wall over the next three years. Trillions of dollars in corporate debt mature before 2027. Much of this corporate debt was issued during zero-interest-rate policy periods.
Refinancing low-coupon debt at current prevailing rates increases interest expense significantly. Debt service obligations will consume larger shares of operating cash flow. Earnings before interest and taxes must rise to offset higher interest expense.
Highly leveraged companies face severe debt structure challenges. Private credit markets offer alternative capital solutions. However, private loans demand steep risk premiums and strict covenants. Borrowers face higher overall capital costs when transitioning from public markets.
Syndicated loan markets mirror these structural pressures. Leveraged loans tied to floating benchmarks experience immediate coupon increases. Interest coverage ratios decline rapidly across vulnerable operational models. Credit downgrades will likely accelerate.
Econometric Forecasting Frameworks for Debt Trajectories
Institutional analysts utilize quantitative models to forecast yield trajectories. Vector Autoregression models track central bank balance sheet runoff rates. Key inputs include bank reserves, reverse repo balances, and sovereign supply forecasts.
Term premium estimation models provide crucial yield curve insights. The Adrian-Crump-Moench model measures term premium changes over time. Unpacking term premium spikes allows traders to isolate real rate movements from inflation expectations.
Credit Default Swap basis spreads offer predictive signals. A positive CDS basis indicates cash market illiquidity relative to synthetic derivatives. Expanding CDS spreads signal imminent secondary market sell-offs before cash market pricing adjusts. Institutional desks monitor these discrepancies closely.
Understanding fundamental debt structures is critical for accurate quantitative modeling. Investors can review core definitions on Investopedia’s Corporate Bond reference page.
Strategic Portfolio Positioning in a Prolonged QT Environment
Fixed income portfolio managers must adopt disciplined positioning tactics. Duration management requires careful structure adjustments. Barbell strategies combine short-term cash equivalents with high-quality long-duration bonds.
Sector selection forms the cornerstone of risk management. Defensive sectors with inelastic consumer demand show strong cash flow stability. Utilities, healthcare, and essential consumer goods handle higher debt costs effectively. Technology and cyclical industrials exhibit higher spread volatility.
An up-in-quality bias remains vital during QT cycles. Moving capital from speculative debt into high-grade corporate paper shields capital. Senior secured instruments provide superior recovery rates during potential default cycles.
Maintaining ample portfolio liquidity is critical. Secondary market illiquidity can prevent quick exits from distressed positions. High cash allocations allow fund managers to capitalize on market dislocations when yield spreads spike unexpectedly.
Macroeconomic Black Swans and Central Bank Pivot Triggers
Quantitative tightening cannot continue indefinitely without structural friction. Funding market disruptions represent the primary operational limit. Spikes in the Secured Overnight Financing Rate signal dangerous liquidity scarcity.
In September 2019, repo market stress forced the Federal Reserve to halt balance sheet reductions. Similar structural fragility exists in current money markets. Rapid bank reserve contraction can suddenly impair clearing and settlement systems.
Financial stability mandates always override inflation targets during system shocks. If systematic market illiquidity threatens treasury market functioning, central banks will intervene. Central banks would pause runoff or resume asset purchases.
Investors must monitor key liquidity indicators continuously. Federal Reserve bank reserves dropping below critical thresholds signal potential policy shifts. Understanding these monetary inflection points protects portfolios from sudden regime shifts.
Conclusion
Quantitative tightening fundamentally alters the trajectory of corporate debt yields. Shrinking central bank balance sheets eliminate artificial liquidity buffers. Corporate issuers must adapt to higher baseline capital costs and wider credit spreads.
Institutional investors must prioritize balance sheet quality, maintain liquidity, and monitor refinancing walls closely. Capital preservation relies on proactive credit analysis and disciplined risk management.
How is your institution adjusting its corporate credit duration to navigate ongoing quantitative tightening dynamics?